


MACRO ECONOMIC CALENDAR 16 – 20 November, 2026 · GMT+8
Weekly Economic Calendar: Week of 16 November – 20 November 2026
Followme News Desk | November 16, 2026 | All times GMT+8
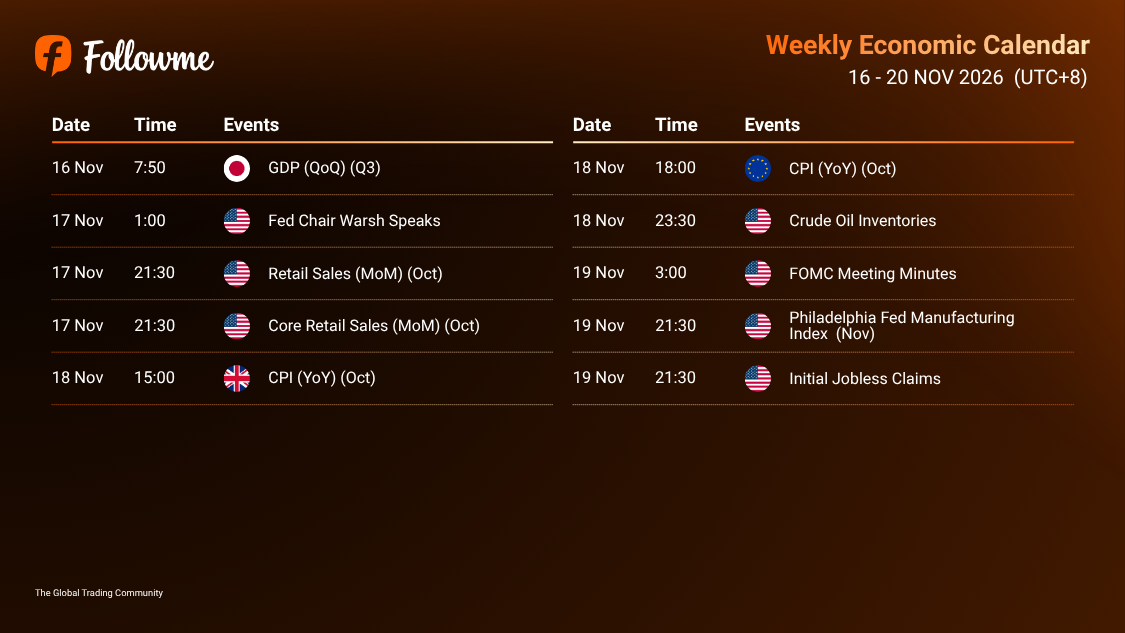
This week's economic calendar is focused on Japan GDP (QoQ) Q3, Fed Chair Warsh's speech, U.S. Retail Sales and Core Retail Sales (MoM), UK CPI (YoY), EU CPI (YoY), Crude Oil Inventories, the FOMC Meeting Minutes, the Philadelphia Fed Manufacturing Index and Initial Jobless Claims. Monday opens with Japan's GDP, Tuesday brings Warsh at 1:00 and retail sales that evening, Wednesday carries the UK and Eurozone inflation figures, and Thursday delivers the FOMC Minutes alongside the Philly Fed and Claims.
The FOMC Minutes are the standout event. The Fed held at 3.75% to 4.00% in October with two dissenters who wanted a hike, and the market has been leaning toward a December move ever since. The minutes show how wide that hawkish group is, and with Warsh deliberately keeping his guidance vague, they're one of the few places where traders get detail. With no rate decision on the calendar, the Fed talk and the consumer data carry the Dollar this week.
Key Events This Week
🕐 All times shown are GMT+8
| Date | Time | CCY | Event | Forecast | Previous |
|---|---|---|---|---|---|
| 16/11 | 07:50 | 🇯🇵 JPY | GDP (QoQ) (Q3) | 0.30% | 0.50% |
| 17/11 | 01:00 | 🇺🇸 USD | ⭐ Fed Chair Warsh Speaks | — | — |
| 21:30 | 🇺🇸 USD | Retail Sales (MoM) (Oct) | 0.30% | 1.30% | |
| 21:30 | 🇺🇸 USD | Core Retail Sales (MoM) (Oct) | 0.60% | 1.40% | |
| 18/11 | 15:00 | 🇬🇧 GBP | CPI (YoY) (Oct) | 3.40% | 3.10% |
| 18:00 | 🇪🇺 EUR | CPI (YoY) (Oct) | 4.00% | 3.80% | |
| 23:30 | 🇺🇸 USD | Crude Oil Inventories | -0.600M | -0.865M | |
| 19/11 | 03:00 | 🇺🇸 USD | ⭐ FOMC Meeting Minutes | — | — |
| 21:30 | 🇺🇸 USD | Philadelphia Fed Manufacturing Index (Nov) | 28.2 | 37.8 | |
| 21:30 | 🇺🇸 USD | Initial Jobless Claims | 194K | 191K |
Macro Analysis
🇯🇵 Japan GDP (QoQ) Q3
Japan's Q3 GDP is forecast at 0.30% on a quarterly basis, down from 0.50% prior. Growth of 0.30% would still be growth, but it's a clear step back after a stronger quarter, and it gives the BoJ something to think about when it weighs how fast to keep normalising. A reading at or above 0.50% would support JPY and keep the tightening story intact. A contraction would be the bigger surprise and would weigh on the yen at the start of a week that's heavy on U.S. central bank talk.
🇺🇸 Fed Chair Warsh Speaks
Fed Chair Warsh speaks at 1:00 on Tuesday morning. There's no forecast for a speech, so the useful question is what tone he's likely to take. Since taking the job in May he has been deliberately vague about where rates go next, and he has said more than once that he won't pre-judge meetings, pointing traders to the data instead. At the October meeting the Fed held at 3.75% to 4.00% with two dissenters who wanted a hike, and the market has been leaning toward a December move ever since. The Fed also has an AI field hearing in the Bay Area on 16 November, so some of the talk may lean toward productivity and technology rather than rates. If Warsh repeats that inflation is above target and the committee will deliver price stability, USD gets support. If he sounds relaxed about the pace of price increases, the Dollar could slip before U.S. trading even opens.
🇺🇸 U.S. Retail Sales and Core Retail Sales
Retail Sales for October are forecast at 0.30%, a sharp slowdown from 1.30% prior, while Core Retail Sales are forecast at 0.60%, down from 1.40%. September beat expectations by a wide margin on both measures, with the headline at 1.30% against a 0.80% forecast and core at 1.40% against 0.60%, so some payback is built into these numbers. The question is how much. Core staying well ahead of the headline usually means autos or gasoline are dragging on the total rather than spending weakening across the board. A beat on either measure would tell traders the consumer is still spending freely, which backs the case for a December hike and supports USD. A miss that takes core below 0.30% would be read as the first sign that high prices are starting to bite.
🇬🇧 UK CPI (YoY)
UK CPI for October is forecast at 3.40%, up from 3.10% prior. That would be another step higher after several months of acceleration, and it leaves the BoE with very little room to talk about easing. A reading at or above 3.40% would support GBP. A miss closer to 3.10% would take some heat out of the BoE's tone and weigh on Sterling. It lands three hours before the Eurozone figure, so the pound and the euro could both move on the same afternoon for different reasons.
🇪🇺 EU CPI (YoY)
Eurozone CPI for October is forecast at 4.00%, up from 3.80% prior. This is the final estimate for the month, following the first release two weeks ago, so the number should already be familiar and any surprise comes from a revision. If the final lands at 4.00%, nothing changes and the ECB's firm tone stays in place. A revision lower, toward 3.80%, would take some support away from EUR. A revision higher would add to the idea that euro-area inflation is still moving the wrong way, and EUR/USD could climb even with the Dollar helped by the Fed talk earlier in the week.
🇺🇸 U.S. Crude Oil Inventories
Crude Oil Inventories are forecast at -0.600M, a smaller drawdown than the -0.865M prior. Another drawdown, even a modest one, keeps the oil market looking tight. A surprise build would be the more notable outcome and could take some pressure off energy prices, which matters when inflation is the main worry. It lands late on Wednesday, after both CPI releases, so it will probably be a side note unless it's a clear outlier.
🇺🇸 FOMC Meeting Minutes
The FOMC Meeting Minutes from the October meeting land on Thursday at 3:00, and they're the standout event of the week. The Fed held at 3.75% to 4.00% in a 10-2 vote, with Governor Cook and Cleveland Fed President Hammack both wanting a quarter-point hike. That split is what traders will be looking for in the minutes: how many other members were close to joining them, and how much of the committee sees a December hike as the natural next step. Warsh has been careful not to signal anything, so the minutes are one of the few places where the debate shows up in detail. A document that reads hawkish, with several members open to tightening, would push December pricing higher and lift USD. If it shows most members comfortable waiting, the Dollar could soften, particularly after the speech earlier in the week.
🇺🇸 U.S. Philadelphia Fed Manufacturing Index
The Philly Fed Manufacturing Index for November is forecast at 28.2, down from 37.8 prior. October printed 37.8 against a 31.3 forecast, so the market has been underestimating this index, and a drop to 28.2 would still be a healthy expansion. A reading at or above 37.8 would say the October strength wasn't a one-off. A drop below 25 would add a soft note to a day that already carries the Fed minutes and Claims.
🇺🇸 U.S. Initial Jobless Claims
Claims are forecast at 194K, up from 191K prior. Both numbers are very low, and with the Fed leaning toward a hike, low layoffs are part of the reason. A reading at or below 194K backs the idea that the labour market can handle tighter policy. A jump above 205K would be hard to square with a hawkish message and would land in the same session as the Fed minutes.
Speculative Outlook for USD Traders
This is a Fed week without a Fed decision. Warsh speaks early on Tuesday, retail sales follow that evening, and the minutes arrive on Thursday morning. Traders went into the week leaning toward a December hike, so each of those three events is really a test of that view. Strong retail sales with a firm Warsh would confirm it and keep the Dollar bid. A weak consumer number or a relaxed tone would start to chip away at it, and the minutes would then decide whether the chipping continues.
Wednesday brings the UK and Eurozone inflation figures, which matter more for GBP and EUR than for USD directly, though both can move the Dollar through the pairs. By Thursday, the minutes carry most of the weight. The two dissents already told the market where the hawks stand, so the question is how wide that group is. A bigger hawkish camp than expected would push December pricing up, and a smaller one would pull it back. Philly Fed and Claims arrive at 21:30 the same day, and they won't change the story unless one of them is a clear surprise.
🟩 Bullish USD Scenario — Stronger Dollar Case
- Warsh Sounds Firm on Inflation — A chair who keeps saying inflation is above target keeps the December hike in play and gives the Dollar support early in the week.
- Minutes Show a Wider Hawkish Camp — If more members than the two dissenters were open to a hike, December pricing moves up and USD follows.
- Retail Sales Beat 0.30% — Spending holding up after a 1.30% jump says the economy can take higher rates.
- Core Retail Sales Hold Near 0.60% — A solid core number on top of September's 1.40% would leave little argument that the consumer is slowing.
- UK CPI Comes in Below 3.40% — A softer UK print weakens the pound and gives USD some relative support in GBP/USD.
- Claims Stay Near 194K — Low layoffs keep the labour market looking strong enough for the Fed to tighten.
🌡 Wild Cards — High Whipsaw Risk
- Warsh Gives Little Away Again — A speech with no guidance could leave USD drifting on Tuesday, then reversing on the minutes when the real detail arrives.
- Retail Sales Split — A weak headline with a strong core would leave traders arguing over which number matters, and USD could flip direction twice within the first hour.
- Minutes Sound Softer Than the Press Conference — If the document reads less hawkish than Warsh did on 28 October, the Dollar could sell off sharply even though the Fed hasn't changed anything.
- EU CPI Revises Away From 4.00% — A change from the first estimate would catch EUR traders off guard and could move EUR/USD against the Dollar's direction.
- UK CPI Beats While EU CPI Misses — Opposite surprises two hours apart would send GBP and EUR in different directions on the same afternoon.
- Japan GDP Contracts — A negative quarter on Monday would hit JPY early and set a nervous tone before the Fed events start.
🔴 Bearish USD Scenario — Weaker Dollar Case
- Warsh Pushes Back on a December Hike — Any hint that the committee is in no hurry would pull rate expectations down and weigh on the Dollar before the U.S. session opens.
- Minutes Show Little Appetite to Hike — If the two dissenters look like outliers, December pricing fades and USD slides.
- Retail Sales Miss Below 0.30% — A bigger payback than expected after a 1.30% month would suggest higher prices are already hurting spending.
- Core Retail Sales Fall Below 0.30% — A weak core reading would be read as the consumer finally slowing, and the case for a hike gets harder to make.
- Philly Fed Drops Below 25 — A sharper fall from 37.8 would add a soft industrial note on the same day as the minutes.
- Claims Rise Above 205K — A clear jump in layoffs would sit badly with any talk of further tightening and leave USD with little support.
Check out the full calendar here: Followme Economic Calendar Tool
Follow Followme for the newest market updates


Peringatan: Pendapat yang disampaikan sepenuhnya merupakan milik penulis dan tidak mencerminkan posisi resmi Followme. Followme tidak bertanggung jawab atas keakuratan, kelengkapan, atau keandalan informasi yang disediakan, serta tidak bertanggung jawab atas tindakan apa pun yang diambil berdasarkan konten ini, kecuali dinyatakan secara tertulis.
- AKHIR -